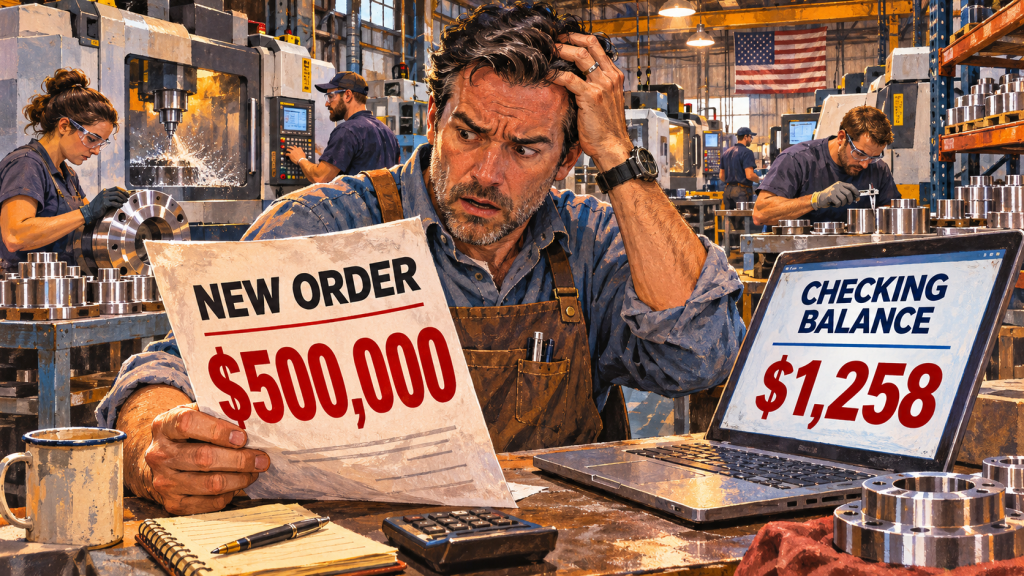
Starting a business takes an idea, excitement and money.
The idea comes from you. The excitement comes from imagining life without a boss. The money may come from savings, home equity, retirement funds or a lender willing to share your enthusiasm.
You open the doors.
Congratulations. You are now the boss, salesperson, collection department and the person who discovers that the toilet is overflowing.
“America’s 36.2 million small businesses employ 62.3 million people—45.9% of the private-sector workforce—and generate 43.5% of the nation’s economic output”
The SBA’s historical figures show that about half of new employer establishments survive five years, and roughly one-third survive ten. Not every closure is a financial failure, but those numbers deserve attention.
That is a lot of America riding on whether the owner can successfully manage and grow the business.
Where do you learn to run one?
Want to become a real estate agent in Florida?
The usual route includes a 63-hour course, a state examination and working under a broker. Then comes 45 hours of post-license education before your first renewal.
Depending on the brokerage, you may also get training, mentors and someone to call when your first transaction resembles a hostage negotiation.
Insurance has a defined pathway, too.
Florida’s standard life-and-health licensing route includes a 60-hour course, a state examination and an appropriate appointment to transact insurance. An established agency may provide training, systems and administrative support.
Neither career guarantees easy money. Both can offer an entry without first financing a storefront, equipment, inventory and an entire payroll.
Nurses and CPAs have their own education, examination and licensing requirements.
Now consider someone opening a small business.
There may be permits, professional licenses and inspections. But there is generally no requirement to demonstrate that you understand pricing, working capital, hiring or a balance sheet.
You can commit your savings before anyone asks whether you know the difference between profit and available cash.
Your qualifications?
“I’m very good at what I do.”
An excellent cook opens a restaurant and suddenly becomes responsible for purchasing, payroll, food costs, marketing and employee disputes.
Yesterday, the question was whether the sauce needed more garlic.
Today, it is whether there is enough cash for Friday’s payroll.
Entrepreneurship programs exist. Small Business Development Centers and SCORE mentors offer guidance. The SBA’s partner network provides free or low-cost counseling and training.
But owners should seek that help before investing the HELOC funds.
SBA-backed lenders may require a business plan, particularly for a startup. The SBA provides guidance, and lenders evaluate repayment ability. But loan approval is not a graduation certificate in business management.
Nor does a plan help much if it goes into a drawer the day the loan closes.
Primary cause of business failures? Lack of cash.
Getting enough to open and getting enough to keep operating are two different calculations.
The equipment costs $40,000. Renovations cost $25,000. The sign looks terrific.
But who pays the employees while you wait for customers to pay you?
That is working capital. Less exciting than the sign, but considerably more useful on payday.
Consider an owner who knows his Tesla’s battery percentage, range, resale value and tire pressure.
Ask about his business’s gross margin, break-even sales or cash needs for the next three months.
“I’d have to ask my accountant.”
He has a dashboard for the car. His business gets a checking-account balance.
“Do you have financial reports?”
“Absolutely. We have QuickBooks.”
“When did you last review them?”
“When the accountant asked why office supplies included a fishing charter.”
Software can produce useful reports. Someone still has to check their accuracy, understand them and use them.
A tax return tells you what happened. A cash forecast helps you prepare for what happens next.
Consider a fictional owner named Mike.
After a terrific fourth quarter, Mike sees a healthy bank balance and takes a substantial owner distribution.
“We earned it. We all worked hard and going to buy a Class A motor home”
Then spring arrives. Mike wins a large contract.
Wonderful news.
He needs employees and supplies now. The customer will pay later.
Mike is busier than ever—and suddenly cannot make payroll.
A business can grow itself into a cash crisis.
Suppose the new contract produces $100,000 in monthly revenue and requires $80,000 in monthly cash expenses. With expenses paid before the customer pays 60 days later, Mike may need roughly $160,000 to bridge two months.
That is a simplified illustration, but the timing problem is real.
The profit is on the report. The payroll comes out of the bank.
Mike calls his banker.
Needing money urgently is most likely not going to happen unless you still have some HELOC funds left. Applying for a new bank loan even if pre-approved most likely won’t fund before Fridays payroll.
Most Businesses fail when they are growing not slowing.
Suggest reviewing financial statements at least monthly.
Most important. Review your CASH FLOW statement daily.
Know what is coming in, what must go out and what must stay in reserve before deciding what you can take home.
Record sales, high profit margin and net income mean nothing if you run out of cash and go out of business like a large proportion of the businesses that don’t make their 5th anniversary.
We celebrate the entrepreneurial leap. We should spend more time helping people prepare for the landing.
Because learning by doing gets expensive when the tuition comes out of your home equity.
We call small businesses the backbone of America. Behind each one may be a family’s savings, a home pledged as collateral and employees counting on Friday’s paycheck.
Yet an owner can take on all that responsibility without ever demonstrating an understanding of cash flow.
By the time the checking account sounds the alarm, the savings may be gone, the credit exhausted and the house at risk.
We celebrate the courage it takes to open the doors.
We need to take the preparation just as seriously.
What if we could improve ten-year business survival from roughly one-third to one-half?
For every 100 businesses started, about 17 more would still be operating ten years later—roughly 50% more survivors.
That could mean more jobs sustained, more economic output and more families preserving what they invested.
The opportunity deserves attention: helping owners manage their businesses could produce benefits far beyond their own checking accounts.
Read more stories at: crazyfamily.blog


Leave a Reply